In New Mexico, an LLC fits when your business earns under $60,000 annually and self-employment tax savings don't justify S-Corp complexity; a S-corp fits when your business consistently earns over $60,000 and you can justify paying yourself a reasonable salary. Compare both structures in detail below.
Affiliate disclosure: We may earn a commission at no extra cost to you.
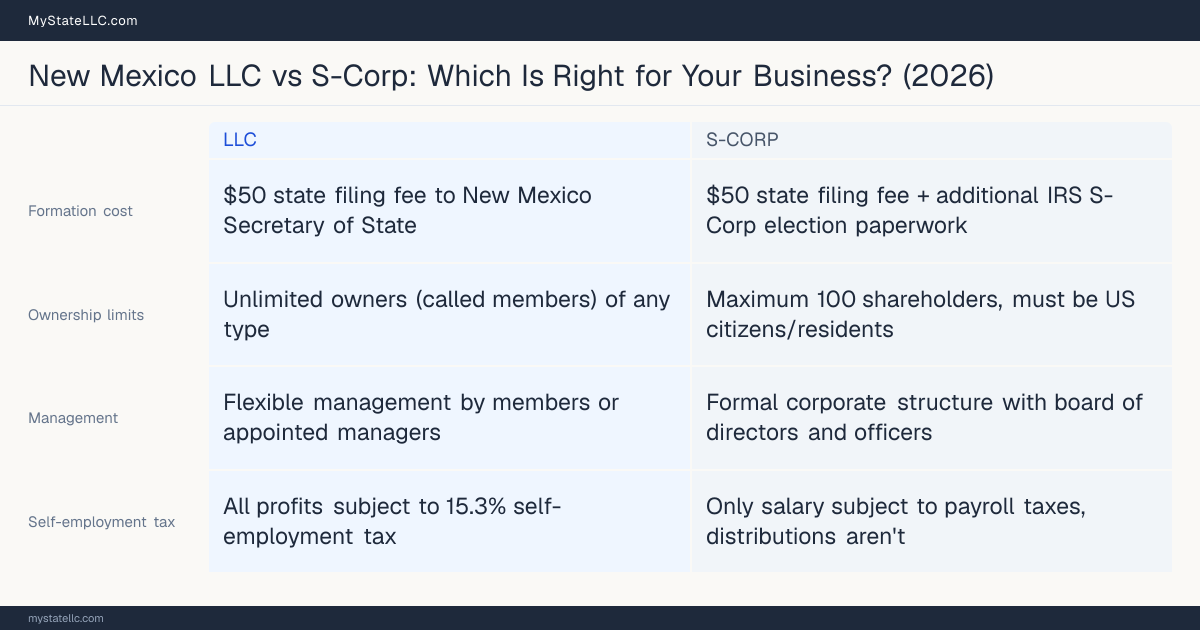
Side-by-side on the factors that decide the choice, for New Mexico. Source: New Mexico Secretary of State.
LLC vs S-Corp: Side-by-Side
Factor
LLC
S-Corp
Formation cost
$50 state filing fee to New Mexico Secretary of State
$50 state filing fee + additional IRS S-Corp election paperwork
Ownership limits
Unlimited owners (called members) of any type
Maximum 100 shareholders, must be US citizens/residents
Management
Flexible management by members or appointed managers
Formal corporate structure with board of directors and officers
Self-employment tax
All profits subject to 15.3% self-employment tax
Only salary subject to payroll taxes, distributions aren't
Payroll required
No payroll requirements for owner-members
Must run payroll and pay reasonable salary to owner-employees
State taxes in New Mexico
Pass-through taxation, members pay personal income tax rates
Pass-through taxation, shareholders pay personal income tax rates
Complexity
Simple ongoing compliance, annual report required
More complex with payroll, quarterly reports, and corporate formalities
Conversion path
Can elect S-Corp tax treatment while keeping LLC legal structure
Can convert to LLC but requires formal dissolution and reformation
When an LLC Makes More Sense
Your business earns under $60,000 annually and self-employment tax savings don't justify S-Corp complexity
You want maximum flexibility in profit distribution among multiple owners
You prefer simple business operations without formal corporate requirements like board meetings
You're a solo entrepreneur or partnership that values operational simplicity over tax optimization
When an S-Corp Makes More Sense
Your business consistently earns over $60,000 and you can justify paying yourself a reasonable salary
You want to minimize self-employment taxes by splitting income between salary and distributions
You're comfortable with payroll responsibilities and additional administrative requirements
You plan to reinvest profits in the business rather than distribute everything to owners
Tax Deep Dive
Llc Default Tax
New Mexico LLCs default to pass-through taxation where all business profits flow to members' personal tax returns. Members pay both income tax and 15.3% self-employment tax on the entire profit amount, regardless of how much they actually withdraw from the business.
S Corp Tax
S-Corps in New Mexico also use pass-through taxation, but owner-employees must receive reasonable salaries subject to payroll taxes. Any remaining profits can be distributed without self-employment tax, creating potential savings for profitable businesses that don't need to distribute all earnings.
Breakeven Income
Most New Mexico businesses see meaningful S-Corp tax savings starting around $60,000 in annual profit, assuming the owner can justify a $40,000 reasonable salary and save self-employment tax on the remaining $20,000 in distributions.
Calculate Your Tax Savings in New Mexico
Enter your profit and filing status to compare estimated annual taxes for LLC, S-Corp, and C-Corp side by side, specific to New Mexico.
This guide is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. It reports published tax rates and statutory attributes, with the sources this page cites. It cannot tell you which structure is better for you: that turns on your profit, the salary you could defend as reasonable compensation, every state you owe tax in, and plans for owners, investors and exit that no figure on this page measures. Confirm your own position with a CPA or tax attorney licensed in your state before you elect anything, because some elections are slow or costly to reverse.
Frequently Asked Questions
Tax savings with an S-Corp election depend entirely on your net income and how you structure distributions. For a New Mexico business earning $80,000 annually, electing S-Corp status through Form 2553 filed with the IRS could save approximately $3,000 in self-employment taxes compared to a default LLC taxed as a sole proprietorship, assuming you pay yourself a $50,000 reasonable salary and distribute $30,000 as dividends. The self-employment tax savings occur because only your W-2 wages are subject to the 15.3% combined Social Security and Medicare tax; distributions avoid this tax entirely. However, New Mexico charges an annual LLC filing fee of $0 through the New Mexico Secretary of State, but S-Corp election requires IRS Form 2553 submission within 2 months and 15 days of tax year start. The practical implication: you'll need payroll processing costs (typically $500 to $1,500 annually) that offset some savings for smaller businesses. Consult a New Mexico CPA to confirm your specific income level justifies S-Corp complexity before filing Form 2553.
To elect S-Corp status for your New Mexico LLC, file IRS Form 2553 (Election by a Small Business Corporation) with the IRS within 2 months and 15 days of the start of the tax year you want the election to take effect, or at any time during the year before it. New Mexico automatically recognizes federal S-Corp elections, administered by the Taxation and Revenue Department rather than the Secretary of State, so you'll pay no separate state filing fee and need no additional state forms beyond your standard LLC filings. This election is critical because it allows your LLC to be taxed as an S-Corporation at the federal level while maintaining your LLC's liability protection under New Mexico law, potentially saving you thousands in self-employment taxes annually if your business generates significant net income. Submit Form 2553 to the IRS service center for your region (typically via mail to the Ogden, Utah processing center). Keep a filed-stamped copy with your business records, as the IRS will issue a confirmation letter acknowledging your election date. Consult a New Mexico tax professional to confirm the election applies retroactively to your desired tax year, since late elections require IRS approval and specific documentation.
Yes, a New Mexico LLC can elect S-Corp taxation by filing Form 2553 (Election by a Small Business Corporation) with the IRS, and that form alone is enough because the election itself treats your LLC as a corporation, so Form 8832 (Entity Classification Election) is not required. This election allows you to retain your LLC's operational flexibility, including your operating agreement and absence of required board meetings, while accessing S-Corp tax benefits like pass-through taxation and potential self-employment tax savings on distributions. The practical advantage is significant: you avoid corporate-level obligations such as New Mexico's flat $50 corporate franchise tax while reducing federal payroll taxes on owner distributions. However, you must file Form 2553 within 2 months and 15 days of the beginning of the tax year you want the election to apply, or at any time during the year before it. Contact the IRS at 1-800-829-1040 or consult a New Mexico tax professional to confirm your filing timeline and ensure proper election setup for your specific situation.
New Mexico follows federal tax treatment for both LLCs and S-Corps, meaning neither structure pays entity-level income tax at the state level. Both enjoy pass-through taxation, where profits flow to owners' personal returns taxed under New Mexico's progressive income tax rates of 1.7% to 5.9%, depending on your bracket. However, the practical difference emerges in self-employment taxes. An LLC taxed as a sole proprietorship or partnership pays self-employment tax on all net profits to the New Mexico Environment Department (NMED) and IRS. An S-Corp election allows you to split income into W-2 wages and distributions, potentially saving 15.3% on self-employment taxes for the distribution portion, savings that compound significantly for profitable businesses. New Mexico imposes a corporate income tax (4.8% up to $500,000, 5.9% above) and a flat $50 corporate franchise tax; it automatically recognizes the federal S election, so electing S-corp status requires no separate state form. Your next step: calculate whether your projected net profit exceeds $60,000 annually, as S-Corp savings typically justify the additional accounting costs above that threshold.
Consider electing S-Corp taxation when your New Mexico LLC consistently earns over $60,000 annually and you can justify paying yourself a reasonable W-2 salary. File Form 2553 (Election by a Small Business Corporation) with the IRS; New Mexico automatically recognizes the federal S election, so no separate state election form is required. The practical benefit: an S-Corp election typically saves 15.3% in self-employment taxes on profits distributed as dividends, though you'll incur $1,500 to $3,000 annually in payroll processing and accounting fees. This creates a breakeven point around $60,000 net profit. Before switching, verify your business structure qualifies, New Mexico LLCs electing S-Corp status must maintain domestic LLC registration and comply with state payroll withholding requirements. Calculate your specific tax savings using the IRS's S-Corp calculator, then contact a New Mexico CPA or the state's Taxation and Revenue Department at (505) 827-0700 to confirm your election timeline and ensure compliance with current requirements.
While not legally required, most New Mexico S-Corp elections benefit from professional guidance, and skipping this step often costs more than the accountant's fee. An accountant helps determine reasonable W-2 salary amounts, critical because the IRS scrutinizes New Mexico S-Corps claiming disproportionately low salaries, and handles payroll setup through the New Mexico Department of Workforce Solutions. They ensure compliance with IRS Form 2553 (Election by a Small Business Corporation) filing deadlines and New Mexico's specific pass-through entity tax requirements under the Gross Receipts Tax Act. Without professional guidance, LLC owners frequently miscalculate estimated tax payments or miss the March 15th corporate tax deadline, creating penalties from the New Mexico Taxation and Revenue Department. An accountant also identifies whether your specific business structure qualifies for New Mexico's small business deductions. To start, contact a New Mexico-licensed CPA who specializes in entity elections and request a consultation focused on your expected business income and ownership structure.
Sources
Each entry below is a document recorded in our verified New Mexico sources, and each entry says what the document is. Some statutory text is read from an accurate mirror rather than from the state's own host, and those say so.
See how Northwest Registered Agent, Bizee, ZenBusiness and LegalZoom, the formation services we partner with, compare on 3-year cost, BBB rating and Trustpilot score before you choose.
Edmond Hui is a software engineer and serial entrepreneur based in New York who has founded multiple online businesses across e-commerce, media, and information publishing. Before transitioning into tech, he spent years as a commercial real estate professional closing deals totaling over 100,000 square feet, giving him firsthand experience with business formation and entity structuring. He built MyStateLLC to provide the free, state-specific LLC guidance he wished existed when forming his own companies.