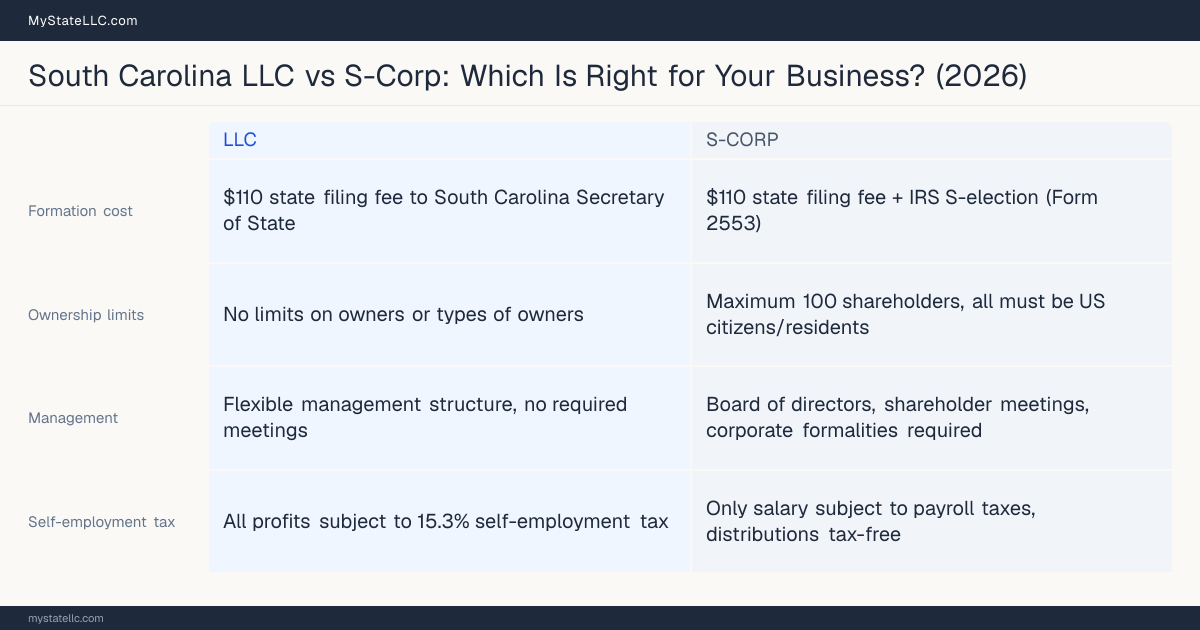
In South Carolina, an LLC fits when you're just starting out and want the simplest, most flexible structure; a S-corp fits when your business generates over $60,000 in annual profit and you want to minimize self-employment taxes. Compare both structures in detail below.
Affiliate disclosure: We may earn a commission at no extra cost to you.
You're just starting out and want the simplest, most flexible structure
Your business profits are under $60,000 annually (self-employment tax savings minimal)
You want multiple types of owners or foreign investors
You prefer minimal paperwork and don't want mandatory meetings or corporate formalities
When an S-Corp Makes More Sense
Your business generates over $60,000 in annual profit and you want to minimize self-employment taxes
You're comfortable with payroll administration and corporate formalities
You've a single owner or few owners who are all US citizens
You want to reinvest profits in the business rather than take all earnings as personal income
Tax Deep Dive
Llc Default Tax
LLCs in South Carolina use pass-through taxation by default, meaning all business profits flow to your personal tax return and are subject to both income tax (up to 7% state rate) and self-employment tax (15.3% federal). This simplicity makes LLCs ideal for smaller businesses.
S Corp Tax
S-Corps split owner compensation into salary (subject to payroll taxes) and distributions (no self-employment tax). You must pay yourself a reasonable salary first, then remaining profits can be taken as tax-free distributions, potentially saving thousands on self-employment taxes.
Breakeven Income
Most South Carolina businesses see S-Corp tax savings when annual profits exceed $60,000. At this level, the self-employment tax savings typically outweigh the added payroll and filing costs.
Calculate Your Tax Savings in South Carolina
Enter your profit and filing status to compare estimated annual taxes for LLC, S-Corp, and C-Corp side by side, specific to South Carolina.
This guide is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. It reports published tax rates and statutory attributes, with the sources this page cites. It cannot tell you which structure is better for you: that turns on your profit, the salary you could defend as reasonable compensation, every state you owe tax in, and plans for owners, investors and exit that no figure on this page measures. Confirm your own position with a CPA or tax attorney licensed in your state before you elect anything, because some elections are slow or costly to reverse.
Frequently Asked Questions
# S-Corp Tax Savings in South Carolina S-Corp election can save you up to 15.3% on self-employment taxes on profits above your reasonable salary. For a business earning $100,000 annually, this could mean $6,000+ in annual tax savings. Here's how it works in South Carolina specifically: You'll file Form 2553 (Election by a Small Business Corporation) with the IRS within 60 days of starting your LLC or by March 15 of the tax year you want the election to apply. South Carolina doesn't impose a separate corporate income tax rate differential. You'll use the standard 21% federal corporate rate, but the self-employment tax savings remain significant at the federal level. The practical trade-off: payroll processing costs $1,500 to $3,000 annually through providers like ADP or Gusto, plus the complexity of filing both corporate and personal returns. You must also pay yourself a "reasonable salary" for your work; the IRS scrutinizes this carefully. For most South Carolina LLCs earning $80,000 or less, the payroll costs eliminate savings, making S-Corp election worthwhile primarily above $100,000 in net profit. Consult a South Carolina CPA to calculate your exact threshold before filing Form 2553.
To elect S-Corp tax status for your South Carolina LLC, file IRS Form 2553 (Election by a Small Business Corporation) with the IRS within 75 days of your LLC's formation date, or by March 15th if you're electing for the current tax year. South Carolina doesn't require a separate state-level election, the Department of Revenue automatically recognizes your federal S-Corp election once the IRS processes Form 2553. This means you'll file one form with one agency instead of managing dual filings. The practical implication is significant: S-Corp status typically reduces self-employment taxes on business profits, though it requires maintaining payroll and quarterly filings. Missing the 75-day deadline requires filing Form 2553 with a late-election request and additional IRS fees. Your next step is consulting a South Carolina tax professional or CPA to confirm your LLC meets S-Corp eligibility requirements (single or multiple members, U.S. ownership) before submitting Form 2553 to the IRS.
Yes, your South Carolina LLC can elect S-Corp tax treatment by filing Form 2553 (Election by a Small Business Corporation) with the IRS within 60 days of business formation or by March 15 of the tax year you want coverage to begin. South Carolina recognizes federal tax elections, so you won't need separate state filing, the state Department of Revenue automatically taxes your LLC according to your federal choice. This election lets you retain LLC liability protection while accessing S-Corp's self-employment tax savings, which typically saves 15.3% on reasonable owner distributions. For profitable South Carolina LLCs earning $60,000+ annually, this often translates to $3,000 to $8,000 yearly in tax savings. However, you'll incur additional accounting costs ($800 to $2,000 annually) for payroll processing and separate tax returns. Consult a South Carolina CPA or tax attorney before filing Form 2553 to confirm your business structure qualifies and timing aligns with your specific situation.
South Carolina treats both LLCs and S-Corps identically for state income tax purposes. Both are pass-through entities taxed at individual rates capped at 7%, with no separate corporate tax. However, the critical difference emerges at the federal level with self-employment taxes, not state taxation. For LLCs, all net income is subject to 15.3% self-employment tax. S-Corps allow you to split income between W-2 wages (subject to employment tax) and distributions (not subject to self-employment tax), potentially saving thousands annually if structured properly. South Carolina's Department of Revenue treats both entities identically during registration. You'll file the Business Tax Application (Form SCDOR-111, via MyDORWAY) for your Retail License and tax accounts regardless of structure. Annual filing fees are $0 for both entity types. This means your state tax bill won't differ, but your federal obligations will. If your LLC generates $100,000 in profit, you pay $15,300 in self-employment tax; an S-Corp could reduce this significantly by paying yourself a reasonable salary and taking the remainder as distributions. File Form 2553 with the IRS immediately after forming an S-Corp to ensure the election applies from day one.
Consider switching to an S-Corp tax election when your annual business profits consistently exceed $60,000, as this is when self-employment tax savings typically justify the added complexity. South Carolina LLCs taxed as S-Corps must file Form 2553 (Election by a Small Business Corporation) with the IRS within 2 months and 15 days of your tax year start to be effective that year. You'll need to register with the South Carolina Department of Revenue and establish a payroll system through the South Carolina Employment Commission. The practical implication is significant: if you earn $80,000 in profits, electing S-Corp status could save you approximately $2,000 annually in self-employment taxes by splitting income between W-2 wages and distributions. However, you'll incur $1,500 to $3,000 yearly in accounting and payroll processing fees through providers like Paychex or ADP. Next, consult a South Carolina CPA to calculate your exact break-even point and file Form 2553 before your deadline.
While not legally required, an accountant is highly recommended for S-Corp tax election in South Carolina. The IRS Form 2553 (Election by a Small Business Corporation) must be filed with the IRS within 60 days of your LLC's formation or tax year start. Missing this deadline can disqualify your election entirely. An accountant will help you determine a reasonable W-2 salary, which the IRS scrutinizes closely; setting it too low invites audit risk, while setting it too high eliminates self-employment tax savings. You'll also face quarterly estimated tax payments to the South Carolina Department of Revenue and payroll tax filings (Form 941) every quarter. Form 1120S tax returns are significantly more complex than Form 1040-SE, requiring Schedule K-1 distributions to owners and precise income allocation. Without professional guidance, mistakes on these filings can result in penalties from both the IRS and South Carolina's Department of Revenue and Taxation. Start by consulting a CPA experienced in South Carolina LLC taxation to evaluate whether S-Corp election truly benefits your specific income level and business structure.
Sources
Each entry below is a document recorded in our verified South Carolina sources, and each entry says what the document is. Some statutory text is read from an accurate mirror rather than from the state's own host, and those say so.
See how Northwest Registered Agent, Bizee, ZenBusiness and LegalZoom, the formation services we partner with, compare on 3-year cost, BBB rating and Trustpilot score before you choose.
Edmond Hui is a software engineer and serial entrepreneur based in New York who has founded multiple online businesses across e-commerce, media, and information publishing. Before transitioning into tech, he spent years as a commercial real estate professional closing deals totaling over 100,000 square feet, giving him firsthand experience with business formation and entity structuring. He built MyStateLLC to provide the free, state-specific LLC guidance he wished existed when forming his own companies.